1. CIBIL Score affects loan approval
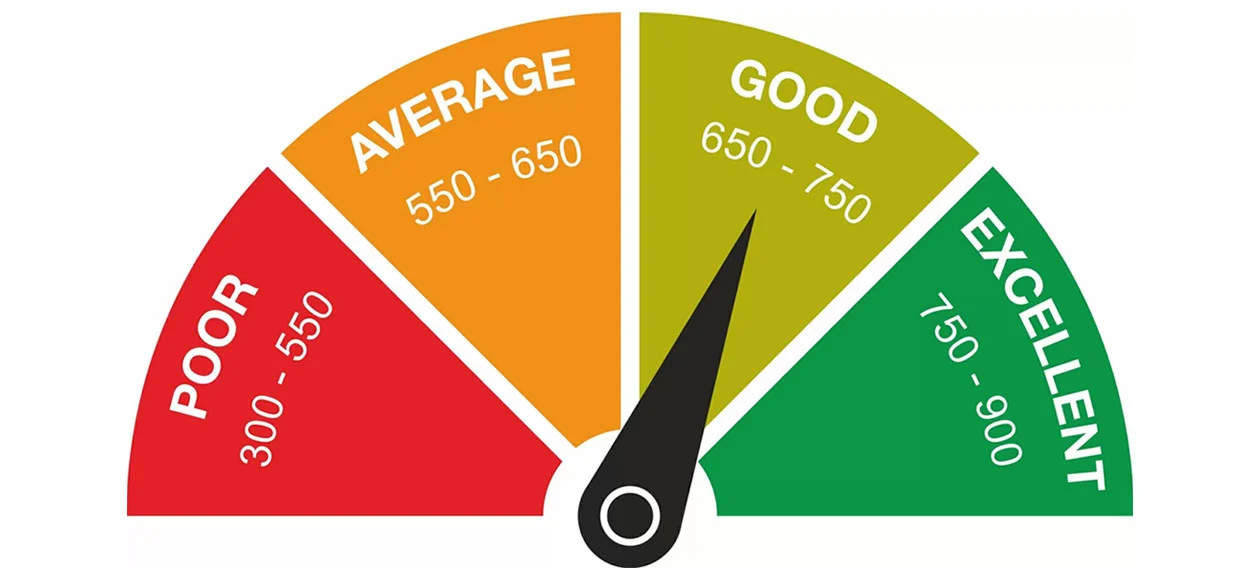
| CIBIL Score | General interpretation | Likely impact
| **750–900** | Excellent | Strong chance of approval
| **700–749** | Good | Generally acceptable
| **650–699** | Moderate | Approval may be possible, but scrutiny may be higher
| **Below 650** | Weak | Approval can be difficult / expensive
| **No score** | Limited credit history | Bank may assess other factors more carefully
*These are general ranges; each lender has its own credit policy.*
2. What does CIBIL tell the lender?
The lender can assess your:
*Previous loan repayment history**
*Credit card payment behaviour**
*Outstanding loans**
*Credit utilisation**
*Number of recent loan/credit applications**
*Existing EMIs**
*Defaults or overdue payments**
*Settled/write-off accounts**, where reported
3. CIBIL is NOT the only factor
A high CIBIL score **does not guarantee** a loan.
Banks/NBFCs also consider:
*CIBIL → Income/Cash Flow → Existing Debt → Business Performance → Banking Transactions → Collateral → GST/ITR → Industry Risk → Loan Purpose**
For a **business loan**, the lender may particularly examine turnover, profitability, GST returns, ITRs, bank statements, existing liabilities and repayment capacity.
4. CIBIL can affect interest rate
A borrower with a strong credit profile may be offered **better interest rates and loan terms**, while a weaker credit profile can result in higher pricing, lower sanctioned amount, additional security/guarantees, or rejection.
5. Important point for business owners
If you are taking a loan for an **existing business**, don't look only at the business's CIBIL/credit history. The lender may examine the **promoters/partners/directors' personal credit histories** as well, depending on the business structure and loan product.
*BizzXchange Learning Series – Loan Tip:**
“CIBIL is not just a score—it is your credit reputation. Before applying for a major business loan, check your CIBIL report, correct errors, avoid unnecessary loan enquiries, and maintain timely EMI/credit-card payments.”**
Dec 02, 2025
Mar 11, 2026
Oct 08, 2026