# CIBIL Score & Credit Management
## Understand Your CIBIL Score and Manage Your Credit Wisely
A good CIBIL Score plays an important role in your financial profile. It helps lenders assess your creditworthiness when you apply for a business loan, personal loan, home loan, or credit card. Effective credit management can help you maintain a healthy credit profile and improve your financial discipline.
### What Is a CIBIL Score?
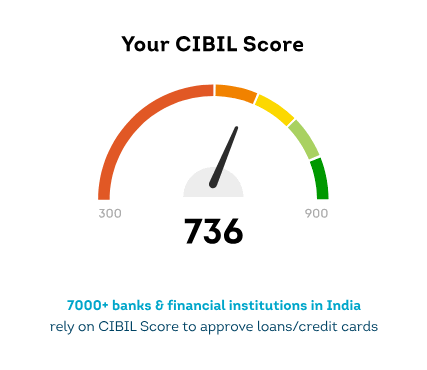
A CIBIL Score is a three-digit number ranging from 300 to 900 that reflects your credit history and repayment behaviour. A higher score generally indicates a stronger credit profile, although loan approval depends on several other factors.
### Why Is Your CIBIL Score Important?
- **Loan Approval:** Lenders consider your credit score when evaluating loan applications.
- **Interest Rates:** A strong credit profile may help you obtain more favourable borrowing terms.
- **Business Financing:** Creditworthiness can be an important factor when seeking business funding.
- **Financial Credibility:** A good repayment history demonstrates responsible credit management.
### How to Maintain and Improve Your CIBIL Score
1. **Pay EMIs and Credit Card Bills on Time:** Avoid late payments and defaults.
2. **Maintain Low Credit Utilisation:** Avoid using a large proportion of your available credit limit.
3. **Monitor Your Credit Report:** Check for incorrect information, unfamiliar accounts, and reporting errors.
4. **Avoid Frequent Loan Applications:** Multiple applications within a short period may affect your credit profile.
5. **Manage Existing Loans:** Maintain a repayment plan based on your income and cash flow.
6. **Avoid Unnecessary Borrowing:** Borrow according to your actual financial requirements and repayment capacity.
7. **Review Outstanding Dues:** Address overdue payments and work towards maintaining a consistent repayment record.
### Credit Management for Businesses
For business owners, credit management is essential for maintaining financial stability and accessing funding opportunities. Proper cash-flow planning, timely repayment of business loans, responsible use of credit facilities, and regular monitoring of outstanding liabilities can help strengthen the overall financial position of a business.
### How Vardhman Taxcon Can Help
Vardhman Taxcon provides professional taxation, accounting, and financial advisory services to help individuals and businesses make informed financial decisions. Proper financial planning, loan assessment, and cash-flow management can support responsible borrowing and better financial control.
**Build a stronger financial future with responsible credit management.**
*Disclaimer: Credit scores are only one factor considered by lenders. Loan approval and interest rates are subject to the lender's eligibility criteria and policies.*
CIBIL Score & Credit Management